
| Strategy | Name / Holdings | Ticker | AUM ($mm) | Inception |
|---|---|---|---|---|
| Core | Alpha Architect U.S. Equity 2 ETF | AAEQ | 473 | 12/09/2025 |
| Core | Alpha Architect U.S. Equity 3 ETF | AAUA | 337 | 03/18/2026 |
| Core | Alpha Architect US Equity 4 ETF | AAUB | 783 | 07/22/2026 |
| Core | Alpha Architect US Equity 5 ETF | AAUD | 275 | 11/19/2026 |
| Core | Alpha Architect U.S. Equity ETF | AAUS | 498 | 07/22/2025 |
| Global Factor | Alpha Architect Global Factor Equity ETF | AAVM | 25 | 05/01/2017 |
| Core | Alpha Architect Aggregate Bond ETF | BOXA | 15 | 12/17/2024 |
| Core | Alpha Architect 1-3 Month Box ETF | BOXX | 14,601 | 12/27/2022 |
| Diversifiers | Alpha Architect Tail Risk ETF | CAOS | 774 | 08/14/2013 |
| Diversifiers | Alpha Architect High Inflation and Deflation ETF | HIDE | 139 | 11/16/2022 |
| Momentum | Alpha Architect International Quantitative Momentum ETF | IMOM | 129 | 12/22/2015 |
| Value | Alpha Architect International Quantitative Value ETF | IVAL | 214 | 12/16/2014 |
| Momentum | Alpha Architect U.S. Quantitative Momentum ETF | QMOM | 372 | 12/01/2015 |
| Value | Alpha Architect U.S. Quantitative Value ETF | QVAL | 704 | 10/21/2014 |
| Total Assets ($mm) |
|---|
| 19,346.07 |
| As of Date |
|---|
| 11/19/2026 |

Address: Suite 150, 3803 West Chester Pike, Newtown Square, PA 19073 | Phone: +1.215.882.9983
Investors should carefully consider the investment objectives, risk, charges, and expenses of the funds. This and other important information is in the indicated fund’s prospectus, which may be obtained by calling (215) 882-9983 or by visiting https://funds.alphaarchitect.com/documents/. The prospectus should be read carefully before investing.
PRINCIPAL INVESTMENT RISKS
An investment in the Funds involves risks, including possible loss of principal. Exchange-traded funds (ETFs) trade like stocks, are subject to investment risk, fluctuate in market value and may trade at prices above or below the ETFs’ net asset value (NAV), and are not individually redeemable directly with the ETFs. Brokerage commissions and ETF expenses will reduce returns. ETFs are subject to specific risks, depending on the nature of the underlying strategy of the Funds, which should be considered carefully when making investment decisions. For a complete description of the Funds’ principal investment risks, please refer to the prospectus.
RISKS COMMON TO ALL FUNDS
ETF Risks.
RISKS COMMON TO QVAL, QMOM, IVAL, IMOM, AAVM, CAOS, HIDE, Cboe:BOXX, AAUS, AAUA, AAEQ, AAUB, AAUD, AAUE
Investment Risk. When you sell your Shares, they could be worth less than what you paid for them. The Fund could lose money due to short-term market movements and over longer periods during market downturns. Securities may decline in value due to factors affecting securities markets generally or particular asset classes or industries represented in the markets. The value of a security may decline due to general market conditions, economic trends, or events that are not specifically related to the issuer of the security or to factors that affect a particular industry or group of industries. During a general downturn in the securities markets, multiple asset classes may be negatively affected. Therefore, you may lose money by investing in the Fund.
RISKS COMMON TO QVAL, QMOM, IVAL, IMOM, AAVM, AAUS, AAUA, AAEQ, AAUB, AAUD, AAUE
Equity Investing Risk. An investment in the Fund involves risks similar to those of investing in any fund holding equity securities, such as market fluctuations, changes in interest rates, and perceived trends in stock prices. The values of equity securities could decline generally or could underperform other investments. In addition, securities may decline in value due to factors affecting a specific issuer, market, or securities markets generally.
RISKS COMMON TO QVAL, QMOM, IVAL, IMOM, AAVM, CAOS, AAUS, AAUA, AAEQ, AAUB, AAUD, AAUE
Large-Capitalization Companies Risk. Large-capitalization companies may trail the returns of the overall stock market. Large-capitalization stocks tend to go through cycles of doing better – or worse – than the stock market in general. These periods have, in the past, lasted for as long as several years. Larger, more established companies may be slow to respond to challenges and may grow more slowly than smaller companies.
RISKS COMMON TO QVAL, QMOM, IVAL, IMOM, AAUS, AAUA, AAEQ, AAUB, AAUD, AAUE
Sector Risk. Companies with similar characteristics may be grouped together in broad categories called sectors. A certain sector may underperform other sectors or the market as a whole. As the Sub-Adviser allocates more of the Fund’s portfolio holdings to a particular sector, the Fund’s performance will be more susceptible to any economic, business or other developments which generally affect that sector.
RISKS COMMON TO BOXA, AAUS, AAUA, AAEQ, AAUB, AAUD, AAUE
Risk of Investing in the United States. Certain changes in the U.S. economy, such as when the U.S. economy weakens or when its financial markets decline, may have an adverse effect on the securities to which the Fund has exposure.
Investment Company Risk. An investment in other registered investment companies (including other ETFs, affiliated and nonaffiliated) is subject to the risks associated with those investment companies, which include, but are not limited to, the risk that such fund’s investment strategy may not produce the intended results; the risk that securities in such fund may underperform in comparison to the general securities markets or other asset classes; and the risk that the fund will be concentrated in a particular issuer, market, industry, or sector, and therefore will be especially susceptible to loss due to adverse occurrences affecting that issuer, market, industry, or sector. Moreover, the Fund will incur duplicative expenses from such investments, bearing its share of that fund’s expenses while also paying its own advisory fees and trading costs. Investments in ETFs are also subject to the “ETF Risks” described herein.
RISKS COMMON TO CAOS, Cboe:BOXX, BOXA, AAUS, AAUA, AAEQ, AAUB
Market Risk. The Fund’s investments are subject to changes in general economic conditions, general market fluctuations, and the risks inherent in investment in interest rate sensitive markets. Interest rate markets can be volatile and prices of investments can change substantially due to various factors including, but not limited to, economic growth or recession, the investment’s average time to maturity, changes in interest rates, changes in the actual or perceived creditworthiness of issuers, and general market liquidity. The Fund is subject to the risk that geopolitical events will disrupt securities markets and adversely affect global economies and markets. Local, regional, or global events such as war, acts of terrorism, the spread of infectious illness or other public health issues, or other events could have a significant impact on the Fund and its investments.
RISKS COMMON TO AAUS, AAUA, AAEQ, AAUB, AAUD, AAUE
Management Risk. The Fund is actively-managed and may not meet its investment objective based on the Sub-Adviser’s or portfolio managers’ success or failure to implement investment strategies for the Fund. The success of the Fund’s investment program depends on the Sub-Adviser and the portfolio managers’ skill in implementing the Fund’s investment strategy. It is important to note that, as part of the security selection process, the Sub-Adviser does not perform any type of fundamental or quantitative analysis on the component companies. Security selection and weighting are driven primarily by a securities market capitalization.
High Portfolio Turnover Risk. The Fund’s investment strategy is expected to result in higher turnover rates. This may increase the Fund’s brokerage commission costs, which could negatively impact the performance of the Fund. Rapid portfolio turnover may expose shareholders to a higher current realization of short-term capital gains, distributions of which would generally be taxed to you as ordinary income and thus cause you to pay higher taxes. In order to effectuate the Fund’s strategy, the Sub-Adviser is relying upon the ability to conduct in-kind redemptions of the Fund’s portfolio holdings. In the event that the Sub-Adviser is unable to do so, the ability of the Sub-Adviser to minimize the taxable income generated by an investment in Fund Shares will be impaired.
Annual Reevaluation Risk. The Fund’s investment universe will be reevaluated annually by the Sub-Adviser. As a result, the Fund’s exposure to one or more securities may be affected by significant price movements promptly following the annual reevaluation. Such lags between re-evaluations may result in significant performance swings relative to the broader equity markets.
Investment Strategy Risk. There is no guarantee that the Fund will be able to successfully minimize the taxable income generated by an investment in Fund Shares.
Counterparty Risk. Counterparty risk is the risk that a counterparty to a financial instrument held by the Fund may become insolvent or otherwise fail to perform its obligations, and the Fund may obtain no or limited recovery of its investment, and any recovery may be significantly delayed. Exchange listed options are issued and guaranteed for settlement by the OCC. The Fund bears the risk that the OCC will be unable or unwilling to perform its obligations under the options contracts. In the unlikely event that the OCC becomes insolvent or is otherwise unable to meet its settlement obligations, the Fund could suffer significant losses. Also, since the Fund is not a member of the OCC (a “clearing member”), and only clearing members can participate directly in the OCC, the Fund will hold options contracts through commingled omnibus accounts at clearing members. As a result, Fund assets deposited with a clearing member as margin for options contracts may, in certain circumstances, be used to satisfy losses of other clients of the Fund’s clearing member. Although clearing members guarantee performance of their clients’ obligations to the OCC, there is a risk that Fund assets might not be fully protected in the event of the clearing member’s bankruptcy.
New Fund Risk. The Fund is a recently organized investment company with no operating history. As a result, prospective investors have no track record or history on which to base their investment decision. There can be no assurance that the Fund will grow to or maintain an economically viable size.
RISKS COMMON TO AAUA, AAEQ, AAUB, AAUD, AAUE, BOXA
Non-Diversification Risk. Because the Fund is non-diversified, it may be more sensitive to economic, business, political or other changes affecting individual issuers or investments than a diversified fund, which may result in greater fluctuation in the value of the Shares and greater risk of loss.
RISKS COMMON TO QVAL, QMOM, IVAL, IMOM, AAVM, HIDE
Management Risk. The Fund is actively managed and may not meet its investment objective based on the SubAdviser’s success or failure to implement investment strategies for the Fund.
Periodic Reallocation Risk. Because the Sub-Adviser will generally reallocate the Fund’s portfolio on a periodic basis, generally each month, (i) the Fund’s market exposure may be affected by significant market movements promptly following the periodic reconstitution that are not predictive of the market’s performance for the subsequent period and (ii) changes to the Fund’s market exposure may lag a significant change in the market’s direction (up or down) by as long as a month if such changes first take effect promptly following the periodic reallocation. Such lags between market performance and changes to the Fund’s exposure may result in significant underperformance relative to the broader equity or fixed income market.
Quantitative Security Selection Risk. Data for some companies may be less available and/or less current than data for companies in other markets. The Sub-Adviser uses quantitative models, and its processes could be adversely affected if erroneous or outdated data is utilized. In addition, securities selected using a quantitative model could perform differently from the financial markets as a whole as a result of the characteristics used in the analysis, the weight placed on each characteristic and changes in the characteristic’s historical trends.
RISKS COMMON TO QVAL, QMOM, IVAL, IMOM, HIDE
High Portfolio Turnover Risk. The Fund’s investment strategy may from time-to-time result in higher turnover rates. This may increase the Fund’s brokerage commission costs, which could negatively impact the performance of the Fund. Rapid portfolio turnover also exposes shareholders to a higher current realization of short-term capital gains, distributions of which would generally be taxed to you as ordinary income and thus cause you to pay higher taxes.
RISKS COMMON TO QVAL, QMOM, IVAL, IMOM, AAVM, AAUS, AAUA, AAEQ, AAUB, AAUD, AAUE
Small- and Mid-Capitalization Company Risk. Investing in securities of small- and mid-capitalization companies involves greater risk than customarily is associated with investing in larger, more established companies. These companies’ securities may be more volatile and less liquid than those of more established companies. Often small- and mid-capitalization companies and the industries in which they focus are still evolving and, as a result, they may be more sensitive to changing market conditions.
RISKS COMMON TO CAOS, Cboe:BOXX, BOXA
Management Risk. The Fund is actively managed and may not meet its investment objective based on the SubAdviser’s success or failure to implement investment strategies for the Fund. In addition, there is the risk that the investment process, techniques and analyses used by the Sub-Adviser will not produce the desired investment results and the Fund may lose value as a result.
Selling or Writing Options. Writing option contracts can result in losses that exceed the seller’s initial investment and may lead to additional turnover and higher tax liability. The risk involved in writing a call option is that there could be an increase in the market value of the underlying or reference asset. An underlying or reference asset may be an index, equity security, or ETF. If this occurs, the call option could be exercised and the underlying asset would then be sold at a lower price than its current market value. In the case of cash settled call options, the call seller would be required to purchase the call option at a price that is higher than the original sales price for such call option. Similarly, while writing call options can reduce the risk of owning the underlying asset, such a strategy limits the opportunity to profit from an increase in the market value of the underlying asset in exchange for up-front cash at the time of selling the call option. The risk involved in writing a put option is that there could be a decrease in the market value of the underlying asset. If this occurs, the put option could be exercised and the underlying asset would then be sold at a higher price than its current market value. In the case of cash settled put options, the put seller would be required to purchase the put option at a price that is higher than the original sales price for such put option.
Box Spread Risk. A Box Spread is the combination of a Synthetic Long position coupled with an offsetting Synthetic Short position through a combination of options contracts on an underlying or reference asset such as index, equity security or ETF with the same expiration date. A Box Spread typically consists of four option positions two of which represent the Synthetic Long and two representing the Synthetic Short. If one or more of these individual option positions are modified or closed separately prior to the option contract’s expiration, then the Box Spread may no longer effectively eliminate risk tied to underlying asset’s movement. Furthermore, the Box Spread’s value is derived in the market and is in part, based on the time until the options comprising the Box Spread expire and the prevailing market interest rates. If the Fund sells a Box Spread prior to its expiration, then the Fund may incur a loss. The Fund’s ability to profit from Box Spreads is dependent on the availability and willingness of other market participants to sell Box Spreads to the Fund at competitive prices.
Counterparty Risk. Counterparty risk is the risk that a counterparty to a financial instrument held by the Fund or by a special purpose or structured vehicle invested in by the Fund may become insolvent or otherwise fail to perform its obligations, and the Fund may obtain no or limited recovery of its investment, and any recovery may be significantly delayed. Exchange listed options, including FLEX Options, are issued and guaranteed for settlement by the Options Clearing Corporation (“OCC”). The Fund’s investments are at risk that the OCC will be unable or unwilling to perform its obligations under the option contract terms. In the unlikely event that the OCC becomes insolvent or is otherwise unable to meet its settlement obligations, the Fund could suffer significant losses.
FLEX Options Risk. FLEX Options are exchange-traded options contracts with uniquely customizable terms like exercise price, style, and expiration date. Due to their customization and potentially unique terms, FLEX Options may be less liquid than other securities, such as standard exchange listed options. In less liquid markets for the FLEX Options, the Fund may have difficulty closing out certain FLEX Options positions at desired times and prices. The value of FLEX Options will be affected by, among others, changes in the underlying share or equity index price, changes in actual and implied interest rates, changes in the actual and implied volatility of the underlying shares or equity index and the remaining time to until the FLEX Options expire. The value of the FLEX Options will be determined based upon market quotations or using other recognized pricing methods. During periods of reduced market liquidity or in the absence of readily available market quotations for the holdings of the Fund, the ability of the Fund to value the FLEX Options becomes more difficult and the judgment of the Fund’s Sub-Adviser (employing the fair value procedures adopted by the Board of Trustees of the Trust) may play a greater role in the valuation of the Fund’s holdings due to reduced availability of reliable objective pricing data.
Valuation Risk. Some portfolio holdings (e.g., FLEX options), potentially a large portion of the Fund’s investment portfolio, may be valued on the basis of factors other than market quotations. This may occur more often in times of market turmoil or reduced liquidity. There are multiple methods that can be used to value a portfolio holding when market quotations are not readily available. The value established for any portfolio holding at a point in time might differ from what would be produced using a different methodology or if it had been priced using market quotations. See “FLEX Options Risk” above for more information regarding potential factors impacting the valuation of FLEX options. Portfolio holdings that are valued using techniques other than market quotations, including “fair valued” securities, may be subject to greater fluctuation in their valuations from one day to the next than if market quotations were used. In addition, there is no assurance that the Fund could sell or close out a portfolio position for the value established for it at any time, and it is possible that the Fund would incur a loss because a portfolio position is sold or closed out at a discount to the valuation established by the Fund at that time.
Tax Risk. The Fund may enter into various transactions, including transactions involving options contracts, for which there is a lack of clear guidance under the Internal Revenue Code of 1986, as amended (the “Code”), which may affect the taxation of the Fund. The use of certain derivatives may cause the Fund to realize higher amounts of ordinary income or short-term capital gain, to suspend or eliminate holding periods of positions, and/or to defer realized losses, potentially increasing the need to make taxable distributions, including those that will be taxed at the rates applicable to ordinary income. For example, exchange-traded options on certain indexes are currently taxed under Code Section 1256 pursuant to which profit and loss with respect to such options are subject to tax as 60% long-term and 40% short-term capital gain or loss regardless of the Fund’s holding period. In addition, certain derivatives are subject to mark-to-market, constructive sale, and straddle provisions of the Code. If such provisions are applicable, there could be an increase (or decrease) in the amount of taxable distributions that will need to be made by the Fund. The Fund intends to qualify as a regulated investment company (“RIC”) under the Code, which requires the Fund to distribute a certain portion of its income and gains each year, among other requirements. Similar to other ETFs, when the Fund disposes of appreciated property by distributing such appreciated property in-kind pursuant to redemption requests of its shareholders under Code Section 852(b)(6), the Fund does not recognize any built-in gain in such appreciated property. If the Internal Revenue Service (“IRS”) or a court disagrees with the Fund’s position as to the applicability of this nonrecognition rule to the Fund’s dispositions, the Fund may not have distributed sufficient income or gains to qualify as a RIC. If, in any year, the Fund fails to qualify as a RIC, the Fund itself generally would be subject to regular corporate U.S. federal income tax, and distributions received by its shareholders would be subject to further U.S. federal income tax. Alternatively, the Fund may be required to pay a deficiency dividend (without having received additional cash) and applicable interest, and such dividend would be paid to the then current shareholders of the Fund. Failure to comply with the requirements for qualification as a RIC would have significant negative economic consequences to the Fund’s shareholders. In addition, the U.S. federal income tax treatment of a derivative may not be as favorable as a direct investment in the underlying asset and may adversely affect the timing, character, and amount of income the Fund realizes from its investments. Additionally, Code Section 1258 requires that certain capital gain from an investment be recharacterized as ordinary income if substantially all of the expected return is attributable to the time value of holding the investment and such investment falls into certain defined categories (a “conversion transaction”). If any of the Fund’s transactions or holding of Shares are deemed to be conversion transactions, certain gains from such transactions or Shares would be treated as ordinary income, which could result respectively in the Fund having not distributed enough income to qualify as a RIC (with the same tax consequences described above) or gain on the disposition of Shares being treated as ordinary income. No assurance can be given that the IRS or a court will not treat any such transactions by the Fund or the holding of Shares as conversion transactions.
RISKS COMMON TO AAUA, AAEQ, AAUB, AAUD, AAUE
In-Kind Contribution Risk. At its launch, the Fund expects to acquire substantially all of its assets through one or more in-kind contributions of securities that are intended to qualify as tax-deferred transactions under Section 351 of the Internal Revenue Code of 1986, as amended (the “Code”). Qualification depends on facts, including whether the contributors as a group own at least 80%
of the Fund’s shares immediately after the contributions and whether each contributor’s securities are sufficiently diversified. Certain facts related to these qualifications are not able to be fully verified by the Fund. In addition, the Internal Revenue Service (“IRS”) has issued a Revenue Ruling stating that it treats a contribution to a newly formed ETF as a taxable exchange of the contributed securities if, as part of a plan including the contribution, the ETF receives cash or securities from an authorized participant (an “AP”) in exchange for shares of the ETF and, shortly thereafter, redeems such shares by distributing the contributed securities to the AP, leaving the ETF with a portfolio materially different from the securities contributed. The IRS and the U.S. Department of the Treasury have also issued guidance describing such transactions as potentially abusive and stating that future guidance could apply retroactively. If a contribution qualifies under Section 351, the Fund generally will take the contributor’s tax basis in the contributed securities, which may be substantially lower than their market value. If the Fund sells those securities, the Fund may generate capital gains that are taxable to all shareholders, including shareholders who did not contribute such securities. If a contribution fails to qualify under Section 351, the contributor could be required to recognize gain, and the Fund may have incorrectly calculated and reported the amount or character of its gains and losses. This could result in the Fund needing to correct tax reporting, recharacterize distributions previously reported to shareholders (for example, from long-term capital gain to ordinary income), pay Fund-level taxes, and incur additional Fund expenses.
RISKS COMMON TO CAOS, Cboe:BOXX, BOXA, AAUS, AAUA, AAUB, AAEQ, AAUD, AAUE
Buying or Purchasing Options Risk. If a call or put option is not sold when it has remaining value and if the market price of the underlying asset, in the case of a call option, remains less than or equal to the exercise price, or, in the case of a put option, remains equal to or greater than the exercise price, the buyer will lose its entire investment in the call or put option. Since many factors influence the value of an option, including the price of the underlying asset, the exercise price, the time to expiration, the interest rate, and the dividend rate of the underlying asset, the buyer’s success in implementing an option buying strategy may depend on an ability to predict movements in the prices of individual assets, fluctuations in markets, and movements in interest rates. There is no assurance that a liquid market will exist when the buyer seeks to close out any option position. When an option is purchased to hedge against price movements in an underlying asset, the price of the option may move more or less than the price of the underlying asset.
RISKS COMMON TO IVAL, IMOM, AAVM, AAUB, AAUD, AAUE
Depositary Receipt Risk. ADRs are generally subject to the risks of investing directly in foreign securities and, in some cases, there may be less information available about the underlying issuers than would be the case with a direct investment in the foreign issuer. ADRs are U.S. dollar-denominated receipts representing shares of foreign-based corporations. Investment in ADRs may be more or less liquid than the underlying shares in their primary trading market. Depositary receipts may be “sponsored” or “unsponsored” and may be unregistered and unlisted. Sponsored depositary receipts are established jointly by a depositary and the underlying issuer, whereas unsponsored depositary receipts may be established by a depositary without participation by the
underlying issuer. Holders of an unsponsored depositary receipt generally bear all the costs associated with establishing the unsponsored depositary receipt. In addition, the issuers of the securities underlying unsponsored depositary receipts are not obligated to disclose material information in the United States and, therefore, there may be less information available regarding
such issuers and there may not be a correlation between such information and the market value of the depositary receipts.
RISKS COMMON TO IVAL, IMOM, AAVM
Foreign Investment Risk. Returns on investments in foreign securities could be more volatile than, or trail the returns on, investments in U.S. securities. Investments in or exposures to foreign securities are subject to special risks, including risks associated with foreign securities generally, including differences in information available about issuers of securities and investor protection standards applicable in other jurisdictions; capital controls risks, including the risk of a foreign jurisdiction imposing restrictions on the ability to repatriate or transfer currency or other assets; currency risks; political, diplomatic and economic risks; regulatory risks; and foreign market and trading risks, including the costs of trading and risks of settlement in foreign jurisdictions.
RISKS COMMON TO QVAL, IVAL, AAVM
Value Style Investing Risk. A value stock may not increase in price if other investors fail to recognize the company’s value and bid up the price, or the markets favor faster-growing companies. Cyclical stocks in which the Fund may invest tend to lose value more quickly in periods of anticipated economic downturns than non-cyclical stocks. Companies that may be considered out of favor, particularly companies emerging from bankruptcy, may tend to lose value more quickly in periods of anticipated economic downturns, may have difficulty retaining customers and suppliers and, during economic downturns, may have difficulty paying their debt obligations or finding additional financing.
RISKS COMMON TO QMOM, IMOM, AAVM
Momentum Style Risk. Investing in or having exposure to securities with the highest relative momentum entails investing in securities that have had above-average recent returns. These securities may be more volatile than a broad cross- section of securities. Returns on securities that have previously exhibited momentum may be less than returns on other styles of investing or the overall stock market. Momentum can turn quickly and cause significant variation from other types of investments, and stocks that previously exhibited high momentum may not experience continued highest relative momentum. In addition, there may be periods when the momentum style is out of favor, and during which the investment performance of the Fund using a momentum strategy may suffer.
RISKS COMMON TO AAUA, AAUD, AAUE
MLP Risk. Investment in MLPs or ETFs that invest in MLPs involves risks that differ from investments in common stock, including risks related to limited control and limited rights to vote on matters affecting the MLP, risks related to potential conflicts of interest between the MLP and the MLP’s general partner, cash flow risks, dilution risks and risks related to the general partner’s right to require unit-holders to sell their common units at an undesirable time or price. Certain MLP securities may trade in lower volumes due to their smaller capitalizations. Accordingly, those MLPs may be subject to more abrupt or erratic price movements and may lack sufficient market liquidity to enable the Fund to effect sales at an advantageous time or without a substantial drop in price. MLPs are generally considered interest-rate sensitive investments. During periods of interest rate volatility, these investments may not provide attractive returns.
RISKS COMMON TO HIDE, Cboe:BOXX, BOXA
Cash and Cash Equivalents Risk. Holding cash or cash equivalents rather than securities or other instruments in which the Fund primarily invests, even strategically, may cause the Fund to risk losing opportunities to earn increased returns, and may cause the Fund to experience potentially lower returns than the Fund’s benchmark or other funds that remain fully invested.
RISKS COMMON TO Cboe:BOXX, BOXA, CAOS
Cash Creation Unit Risk. Unlike most other ETFs, the Fund expects to effect a substantial portion of its creations for cash, rather than in-kind securities. As a result, an investment in the Fund may be less tax-efficient than an investment in an ETF that effects its creations and redemptions only in-kind. ETFs are able to make in-kind redemptions and avoid being taxed on gains on the distributed portfolio securities at the fund level. A Fund that effects redemptions for cash may be required to sell portfolio securities in order to obtain the cash needed to distribute redemption proceeds. Any recognized gain on these sales by the Fund will generally cause the Fund to recognize a gain it might not otherwise have recognized, or to recognize such gain sooner than would otherwise be required if it were to distribute portfolio securities only in-kind. The Fund intends to distribute these gains to shareholders to avoid being taxed on this gain at the fund level. The use of cash creations may also cause the Fund’s shares to trade in the market at greater bid-ask spreads or greater premiums or discounts to the Fund’s NAV. As a practical matter, only institutions and large investors, such as market makers or other large broker dealers, create or redeem shares directly through the Fund. Most investors will buy and sell shares of the Fund on an exchange through a broker-dealer. Furthermore, cash creation transactions may result in certain brokerage, tax, execution, price movement and other costs and expenses related to the execution of trades resulting from such transactions. To the extent that the maximum additional charge for creation transactions is insufficient to cover these costs and expenses, the Fund’s performance could be negatively impacted.
RISKS COMMON TO Cboe:BOXX, BOXA
Large Shareholder Risk. Certain large shareholders, including other funds advised by the Adviser, Alpha Architect, and/or Arin, may from time to time own a substantial amount of the Fund’s Shares. Any such investment may be held for a limited period of time. There can be no assurance that any large shareholder will not redeem its investment. Dispositions of a large number of Shares by such shareholders, which may occur rapidly or unexpectedly, may adversely affect the Fund’s liquidity and net assets to the extent such transactions are executed directly with the Fund in the form of redemptions through an authorized participant, rather than executed in the secondary market. To the extent effected in cash, these redemptions may also force the Fund to sell portfolio securities when it might not otherwise do so, which may negatively impact the Fund’s NAV and increase the Fund’s brokerage costs. Such cash redemptions may also accelerate the realization of taxable income to shareholders. Similarly, large Fund share purchases through an authorized participant may adversely affect the performance of the Fund to the extent that the Fund is delayed in investing new cash or otherwise maintains a larger cash position than it ordinarily would. If these large shareholders transact in Shares on the secondary market, such transactions may account for a large percentage of the Fund’s trading volume and may, therefore, have a material upward or downward effect on the market price of the Shares.
Frequent Trading Risk. The Fund may engage in active and frequent trading of portfolio securities to achieve its investment objective. This frequent trading of portfolio securities may increase the amount of commissions that the Fund pays when it buys and sells such portfolio securities, which may detract from the Fund’s performance. Derivative instruments and instruments with a maturity of one year or less at the time of acquisition are excluded from the calculation of the Fund’s portfolio turnover rate.
RISKS COMMON TO CAOS, HIDE
Derivatives Risk. A derivative is any financial instrument whose value is based on, and determined by, another asset, rate or index (i.e., stock options, futures contracts, caps, floors, etc.). When the Fund obtains exposure to derivatives it will be exposed to the risks of those derivatives. The use of derivatives for non-hedging purposes may be considered to carry more risk than other types of investments. Unfavorable changes in the value of the underlying asset, rate or index may cause sudden losses. Changes in the value of a derivative may not correlate perfectly with the underlying asset, rate or index, a the Fund could lose more than the principal amount invested. Derivative instruments are subject to a number of risks including counterparty, liquidity, interest rate, market, credit and management risks, as well as the risk of improper valuation.
Asset Allocation Risk. The Fund is also subject to asset allocation risk, which is the chance that the selection of investments, and the allocation of assets to such investments, will cause the Fund to underperform other funds with a similar investment objective.
RISKS COMMON TO AAVM, HIDE
Fund of Funds Risk. The Fund’s investment performance will largely depend on the investment performance of the selected underlying funds. An investment in the Fund is subject to the risks associated with the underlying funds that then-currently comprise the Fund’s portfolio. At times, certain of the segments of the market represented by the Fund’s underlying funds may be out of favor and underperform other segments. The Fund will indirectly pay a proportional share of the expenses of the underlying funds in which it invests (including operating expenses and management fees), which are identified in the fee schedule above as “Acquired Fund Fees and Expenses.”
RISKS COMMON TO HIDE, BOXA
Fixed Income Risk. The market value of fixed income securities will change in response to interest rate changes and other factors, such as changes in the effective maturities and credit ratings of fixed income investments. During periods of falling interest rates, the values of outstanding fixed income securities and related financial instruments generally rise. Conversely, during periods of rising interest rates, the values of such securities and related financial instruments generally decline. Fixed income investments are also subject to credit risk. The longer the effective maturity and duration of the Fund’s portfolio, the more the Fund’s share price is likely to react to changes in interest rates. (Duration is a weighted measure of the length of time required to receive the present value of future payments, both interest and principal, from a fixed income security.)
Interest Rate Risk. Interest rates rise and fall over time. As with any investment whose yield reflects current interest rates, the fund’s yield will change over time. During periods when interest rates are low, the Fund’s yield (and total return) also may be low. Changes in interest rates also may affect the Fund’s share price: a rise in interest rates generally causes the Fund’s share price to fall. The longer the Fund’s portfolio duration, the more sensitive to interest rate movements its share price is likely to be. Also, a change in a central bank’s monetary policy or economic conditions, among other things, may result in a change in interest rates, which could have sudden and unpredictable effects on the markets and significantly impact the value of fixed-income securities in which the Fund invests. A sudden or unpredictable rise in interest rates may cause volatility and the value of fixed-income securities to decline.
Credit Risk. A decline in the credit quality of an issuer, guarantor or liquidity provider of a portfolio investment or a counterparty could cause the fund to lose money or underperform. The Fund could lose money if, due to a decline in credit quality, the issuer, guarantor or liquidity provider of a portfolio investment or a counterparty fails to make, or is perceived as being unable or unwilling to make, timely principal or interest payments or otherwise honor its obligations.
RISKS SPECIFIC TO CAOS
Equity Securities Risk. Investments in securities whose performance is linked to that of equity securities, such as SPX Options, may fluctuate in value in response to many factors, including the activities of the individual issuers included in the Index, general market and economic conditions, interest rates, and specific industry changes. Such price fluctuations subject the Fund to potential losses.
U.S. Government Securities Risk. U.S. government securities risk refers to the risk that debt securities issued or guaranteed by certain U.S. Government agencies, instrumentalities, and sponsored enterprises are not supported by the full faith and credit of the U.S. Government, and so investments in their securities or obligations issued by them involve credit risk greater than investments in other types of U.S. Government securities.
Leverage Risk. Leverage risk refers to the potential for increased volatility and losses in a portfolio due to the use of derivatives or other financial instruments that may magnify gains and losses beyond the initial investment. The Fund will utilize derivatives, such as options, to gain exposure to certain assets or markets with a smaller initial investment. While leveraging derivatives can amplify gains, it can also magnify losses significantly. Leverage could possibly create increased volatility for the Fund.
Cash and Cash Equivalents Risk. At any time, the Fund may have significant investments in cash or cash equivalents. When a substantial portion of a portfolio is held in cash or cash equivalents, there is the risk that the value of the cash account, including interest, will not keep pace with inflation, thus reducing purchasing power over time.
Investment Company Risk. An investment in other registered investment companies (including other ETFs, affiliated and non-affiliated) is subject to the risks associated with those investment companies, which include, but are not limited to, the risk that such fund’s investment strategy may not produce the intended results; the risk that securities in such fund may underperform in comparison to the general securities markets or other asset classes; and the risk that the fund will be concentrated in a particular issuer, market, industry or sector, and therefore will be especially susceptible to loss due to adverse occurrences affecting that issuer, market, industry or sector. Moreover, the Fund will incur duplicative expenses from such investments, bearing its share of that fund’s expenses while also paying its own advisory fees and trading costs. Investments in ETFs are also subject to the “ETF Risks” described herein. In addition, the Fund may invest in underlying funds which invest a larger portion of their assets in one or more sectors than many other funds, and thus will be more susceptible to negative events affecting those sectors. The Fund may invest in affiliated ETFs managed by the Adviser, Alpha Architect, and/or Arin, including the 1-3 Month Box ETF. The Adviser, Alpha Architect, and/or Arin may be subject to potential conflicts of interest in selecting underlying funds because the fees paid to it by certain affiliated underlying funds are higher than the fees paid by other affiliated and unaffiliated underlying funds. To the extent the Fund invests a significant percentage of its assets in any one affiliated ETF or across multiple affiliated ETFs, the Fund will be subject to a greater degree to the risks particular to the investment strategies employed by the Adviser, Alpha Architect, and/or Arin.
RISKS SPECIFIC TO HIDE
Commodity Risk. Investing in physical commodities is speculative and can be extremely volatile. Market prices of commodities may fluctuate rapidly based on numerous factors, including: changes in supply and demand relationships (whether actual, perceived, anticipated, unanticipated or unrealized); weather; agriculture; trade; domestic and foreign political and economic events and policies; diseases; pestilence; technological developments; currency exchange rate fluctuations; and monetary and other governmental policies, action and inaction. When the Fund obtains exposure to commodities through its investments in other underlying funds, it will be indirectly exposed to the foregoing risks.
Commodity-Linked Derivatives Risk. The Fund seeks to gain exposure to commodity markets by investing in underlying funds that have exposure to commodities and this may include exposure to commodity-linked derivatives. The value of a commodity-linked derivative investment is typically based upon the price movements of a physical commodity (such as heating oil, precious metals, livestock, or agricultural products), a commodity futures contract or commodity index, or some other readily measurable economic variable. Commodity-linked derivatives provide exposure, which may include long and/or short exposure, to the investment returns of physical commodities that trade in the commodities markets without investing directly in physical commodities. The value of commodity-linked derivative instruments may be affected by changes in overall market movements, volatility of the underlying Index, changes in interest rates, or factors affecting a particular industry or commodity, such as drought, floods, weather, livestock disease, embargoes, tariffs and international economic, political and regulatory developments. The value of commodity-linked derivatives will rise or fall in response to changes in the underlying commodity or related index. Investments in commodity-linked derivatives may be subject to greater volatility than non-derivative based investments. A highly liquid secondary market may not exist for certain commodity-linked derivatives, and there can be no assurance that one will develop.
Commodity Futures Risk. The Fund seeks to gain exposure to commodity markets by investing in underlying funds that have exposure to commodities and this may include exposure to commodity futures. Risks of commodity futures include: (i) an imperfect correlation between the value of the futures contract and the underlying commodity or commodity index; (ii) possible lack of a liquid secondary market; (iii) the inability to close a futures contract when desired; (iv) losses caused by unanticipated market movements, which may be unlimited; and (v) an obligation for the investor to make daily cash payments to maintain its required collateral, or margin, particularly at times when the investor may have insufficient cash or must sell securities to meet those margin requirements. Although the counterparty to an exchange-traded futures contract is often backed by a futures commission merchant (“FCM”) or clearing organization that is further backed by a group of financial institutions, there may be instances in which the FCM or the clearing organization could fail to perform its obligations, causing significant losses to the investor.
Commodity Swaps Risk. The Fund seeks to gain exposure to commodity markets by investing in underlying funds that have exposure to commodities and this may include exposure to commodity swaps. If a counterparty to a commodity swap agreement becomes bankrupt or otherwise fails to perform its obligations under the commodity swap due to financial difficulties, the Fund could suffer losses. Central clearing is designed to reduce counterparty credit risk compared to uncleared commodity swaps because central clearing interposes the central clearinghouse as the counterparty to each participant’s swap, but it does not eliminate those risks completely. Credit risk of cleared commodity swap participants is concentrated in a few clearinghouses and the consequences of insolvency of a clearinghouse are not clear. Commodity Swaps are subject to pricing risk (i.e., commodity swaps may be hard to value) and may be considered illiquid.
Commodity-Linked Note Risk. The Fund seeks to gain exposure to commodity markets by investing in underlying funds that have exposure to commodities and this may include exposure to commodity-linked notes. Commodity-linked notes have characteristics of both a debt security and a derivative. Typically, they are issued by a bank at a specified face value and pay a fixed or floating rate linked to the performance of an underlying asset, such as commodity indices, particular commodities or commodity futures contracts. As such, an investor faces the economic risk of movements in commodity prices by investing in such notes. These notes also are subject to credit, market and interest rate risks that in general affect the values of debt securities.
Real Estate Investment Risk. Companies in the real estate sector include companies that invest in real estate, such as real estate investment trusts (REITs) and real estate management and development companies. Companies that invest in real estate are subject to the risks of owning real estate directly as well as to risks that relate specifically to the way that such companies operate, including management risk (such companies are dependent upon the management skills of a few key individuals and may have limited financial resources). Adverse economic, business or political developments affecting real estate could have a major effect on the value of an underlying fund’s investments. Investing in real estate is subject to such risks as decreases in real estate values, overbuilding, increased competition and other risks related to local or general economic conditions, increases in operating costs and property taxes, changes in zoning laws, casualty or condemnation losses, possible environmental liabilities, regulatory limitations on rent, possible lack of availability of mortgage financing, market saturation, fluctuations in rental income and the value of underlying properties and extended vacancies of properties. Certain real estate securities have a relatively small market capitalization, which may tend to increase the volatility of the market price of these securities. Real estate securities have limited diversification and are, therefore, subject to risks inherent in operating and financing a limited number of projects. Real estate securities are also subject to heavy cash flow dependency and defaults by borrowers or tenants. The Fund’s investments in REITs are subject to additional risks, such as poor performance by the manager of the REIT or failure by the REIT to qualify for tax-free pass through of income under the Code.
Risk of U.S. Treasury Bills. Direct obligations of the U.S. Treasury have historically involved little risk of loss of principal if held to maturity. However, due to fluctuations in interest rates, the market value of such securities may vary.
Leverage Risk. The Fund does not seek leveraged returns but as a result of the Fund’s investments in underlying funds that use certain derivatives it may create investment leverage. As a result, the use of these derivatives by the underlying funds may magnify losses to the Fund, and even a small market movement may result in significant losses to the Fund.
Investment Company Risk. An investment in other registered investment companies (including other ETFs, affiliated and non-affiliated) is subject to the risks associated with those investment companies, which include, but are not limited to, the risk that such fund’s investment strategy may not produce the intended results; the risk that securities in such fund may underperform in comparison to the general securities markets or other asset classes; and the risk that the fund will be concentrated in a particular issuer, market, industry or sector, and therefore will be especially susceptible to loss due to adverse occurrences affecting that issuer, market, industry or sector. Moreover, the Fund will incur duplicative expenses from such investments, bearing its share of that fund’s expenses while also paying its own advisory fees and trading costs. Investments in ETFs are also subject to the “ETF Risks” described herein. In addition, the Fund may invest in underlying funds which invest a larger portion of their assets in one or more sectors than many other funds, and thus will be more susceptible to negative events affecting those sectors. The Fund may invest in affiliated ETFs managed by the Adviser and/or Alpha Architect. The Adviser and/or Alpha Architect may be subject to potential conflicts of interest in selecting underlying funds because the fees paid to it by certain affiliated underlying funds are higher than the fees paid by other affiliated and unaffiliated underlying funds. To the extent the Fund invests a significant percentage of its assets in any one affiliated ETF or across multiple affiliated ETFs, the Fund will be subject to a greater degree to the risks particular to the investment strategies employed by the Adviser and/or Alpha Architect.
RISKS SPECIFIC TO BOXA
Investment Risk. When you sell your Shares of the Fund, they could be worth less than what you paid for them. The Fund could lose money due to short-term interest rate market movements and over longer periods during continued interest rate market movements. Therefore, you may lose money by investing in the Fund.
Combo Risk. A combo represents a combination of call and put options to produce a synthetic long or synthetic short position. A combined transaction will usually contain elements of risk that are present in each of its component transactions (See Options Risk). Although combined transactions are normally entered into based on the Sub-Advisers’ judgment that the combined strategies will more effectively achieve the desired portfolio management goal, it is possible that the combination will instead increase such risks or hinder achievement of the portfolio management objective. The Fund’s ability to utilize Combos effectively is dependent on the availability and willingness of other market participants to purchase or sell Combos from the Fund at competitive prices.
U.S. Treasury Obligations Risk. The Fund may have exposure to U.S. Treasury obligations. U.S. Treasury obligations may differ from other securities in their interest rates, maturities, times of issuance and other characteristics and may provide relatively lower returns than those of other securities. Similar to other issuers, changes to the financial condition or credit rating of the U.S. government may cause the value of the Fund’s U.S. Treasury obligations to decline.
U.S. Agency Mortgage-Backed Securities Risk. The Fund may have exposure to MBS issued or guaranteed by the U.S. government or one of its agencies or sponsored entities, some of which may not be backed by the full faith and credit of the U.S. government. MBS represent interests in “pools” of mortgages and are subject to interest rate, prepayment, and extension risk. MBS react differently to changes in interest rates than other bonds, and the prices of MBS may reflect adverse economic and market conditions. Small movements in interest rates (both increases and decreases) may quickly and significantly reduce the value of certain MBS. MBS are also subject to the risk of default on the underlying mortgage loans, particularly during periods of economic downturn.
Extension Risk. During periods of rising interest rates, certain debt obligations may be paid off substantially more slowly than originally anticipated and the value of those securities may fall sharply, resulting in a decline in the Fund’s income and potentially in the value of the Fund’s investments.
Prepayment Risk. During periods of falling interest rates, issuers of certain debt obligations may repay principal prior to the security’s maturity, which may cause the Fund to have to reinvest in securities with lower yields or higher risk of default, resulting in a decline in the Fund’s income or return potential.
Underlying Alpha Architect ETFs Risk. The Fund may invest a portion of its in the 1-3 Month Box ETF, so the Fund’s investment performance is likely to be directly impacted by the performance of the 1-3 Month Box ETF. The Fund’s NAV will change with changes in the value of the 1-3 Month Box ETFs and other instruments in which a Fund invests based on their market valuations.
New Fund Risk. The Fund is a recently organized investment company with limited operating history. As a result, prospective investors have a limited track record or history on which to base their investment decision. There can be no assurance that the Fund will grow to or maintain an economically viable size.
RISKS SPECIFIC TO Cboe:BOXX
Low Short-Term Interest Rates Risk. During market conditions in which short-term interest rates are at low levels, the Fund’s yield can be very low, and the Fund may have a negative yield (i.e., it may lose money on an operating basis). During these conditions, it is possible that the Fund will generate an insufficient amount of income to pay its expenses. In addition, it is possible that during these conditions the Fund may experience difficulties purchasing and/or selling securities, and may, as a result, maintain a portion of its assets in cash, on which it may earn little, if any, income.
RISKS SPECIFIC TO AAVM
Portfolio Size Risk. Pursuant to the Sub-Adviser’s methodology, the Fund’s portfolio is composed of a relatively small number of constituents. To the extent that a significant portion of the Fund’s total assets is invested in a limited number of holdings, the appreciation or depreciation of any one holding of the Fund may have a greater impact on the Fund’s NAV than it would if the Fund’s portfolio was comprised of a greater number of constituents.
Underlying Alpha Architect ETFs Risk. The Fund expects to invest a substantial portion of its assets in the Underlying Alpha Architect ETFs, so the Fund’s investment performance is likely to be directly related to the performance of the Underlying Alpha Architect ETFs. The Fund’s NAV will change with changes in the value of the Underlying Alpha Architect ETFs and other instruments in which the Fund invests based on their market valuations.
TAX-RELATED MATTERS
Neither Alpha Architect nor its affiliates provide tax advice.
Section 351 of the Internal Revenue Code (IRC) allows an investor to contribute a portfolio of securities with unrealized gains to a newly formed ETF taxed as a regulated investment company (RIC) without recognizing those gains at the time of contribution, provided certain conditions are met. Among them, Treasury Regulation §1.351-1(c)(6) requires that each contributing investor transfer a diversified portfolio under the tests of IRC §368(a)(2)(F)(ii): no more than 25% of the portfolio’s value in the securities of any one issuer and no more than 50% in the securities of five or fewer issuers, with members of a controlled group treated as one issuer. The rules governing a §351 exchange involving securities are complex. Investors should consult a tax advisor or tax attorney before participating to ensure compliance and avoid unintended tax consequences. Nothing herein should be construed or relied upon as tax, legal, or financial advice.
IRS Circular 230 disclosure. To ensure compliance with requirements imposed by the IRS, we inform you that any tax advice contained in this communication was not intended or written to be used, and cannot be used, for the purpose of (i) avoiding tax-related penalties under the Internal Revenue Code or (ii) promoting, marketing or recommending to another party any matters addressed herein. You should seek advice based on your particular circumstances from an independent tax advisor.
Estate Planning Notice. The information contained in this communication is not meant to substitute for a thorough estate planning and is not meant to be legal and/or estate advice. It is intended to provide you with a preliminary outline of your goals. Please consult your legal counsel for additional information.
DEFINITIONS
Basis Points (bps). A basis point is a standardized unit used to quote percentages. One basis point equals 0.01% (one one-hundredth of one percent). Therefore, 100 basis points = 1%. Basis points help express small movements or differences with precision. For example, a change from 4.25% to 4.50% is an increase of 25 basis points.
The Funds are distributed by PINE Distributors LLC. The Funds’ investment adviser is Empowered Funds, LLC dba EA Advisers. Alpha Architect, LLC serves as sub-adviser to the Funds. Arin Risk Advisors, LLC also serves as a sub-adviser to the Alpha Architect Tail Risk ETF (CAOS). PINE Distributors LLC is not affiliated with Empowered Funds, LLC, Alpha Architect, LLC, or Arin Risk Advisors, LLC.
ETFAC-5033016-12/25; ETFAC-5047689-12/25; ETFAC-5044558-12/25; ETFAC-5300690-3/26; ETFAC-5292675-3/26; ETFAC-5407605-4/26; ETFAC-5711549-7/26; ETFAC-5830654-8/26; ETFAC-5885653-9/26
Lead Portfolio Manager (Arin Risk Advisors, LLC)
Ryan is the lead portfolio manager for Arin Risk Advisors, LLC. He previously served as a Market Maker and Proprietary Trader with Bullock Capital and Susquehanna International Group across equities, options, and futures markets.
BS in Business Administration, magna cum laude, from Drexel University
Tail Risk (CAOS)
1-3 Mo. Box (Cboe: BOXX)
US Aggregate Bond Box (BOXA)
Trading Director (Arin Risk Advisors, LLC)
Larry oversees all trading across Arin Risk Advisors’ strategies. Previously, he was a market maker/index/sector correlation and dispersion trader with Susquehanna International Group.
BS in Statistics and Economics from Rutgers University
MA in Taxation from New York University School of Law
JD from Villanova
Tail Risk (CAOS)
1-3 Mo. Box (Cboe: BOXX)
US Aggregate Bond Box (BOXA)
Chief Market Strategist (Arin Risk Advisors, LLC)
Joe leads strategy design and risk management for Arin Risk Advisors, LLC, an Alpha Architect sub-adviser. Previously, Joe held similar strategist and portfolio manager positions with SEI Investments, Evergreen Investments, Wachovia, and Vector Capital Management.
BS in Economics from Indiana University of Pennsylvania
MA Economics from Temple University
Tail Risk (CAOS)
1-3 Mo. Box (Cboe: BOXX)
US Aggregate Bond Box (BOXA)
CEO, co-CIO, Portfolio Manager
Wes’s interest in bridging the research gap between academia and industry led him to found Alpha Architect, an asset management firm dedicated to an impact mission of empowering investors through education. He is a contributor to multiple industry publications and regularly speaks to professional investor groups across the country.
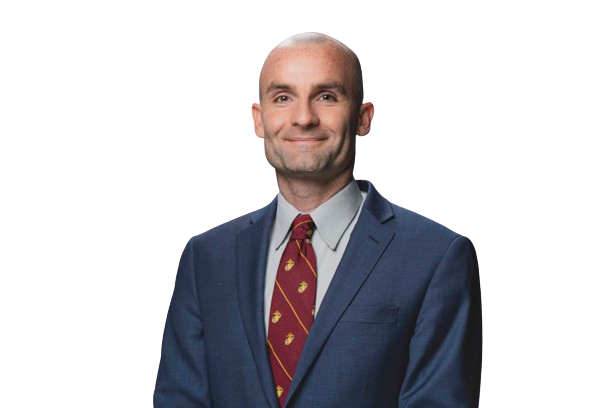
PhD/MBA from the University of Chicago – Booth School of Business; studied under Nobel Prize Winner Eugene Fama
BS in Economics, magna cum laude, from The Wharton School – University of Pennsylvania
United States Marine Corps Captain (2004-2008)
US Quantitative Value (QVAL)
US Quantitative Momentum (QMOM)
International Quantitative Value (IVAL)
International Quantitative Momentum (IMOM)
High Inflation & Deflation (HIDE)
Value Momentum Trend (VMOT)
Analyzing Valuation Measures: A Performance Horse Race over the Past 40 Years | Wes Gray, PhD, Jack Vogel, PhD
Why Do Enterprise Multiples Predict Expected Stock Returns? Steven S. Crawford, Wes Gray, PhD, Jack Vogel, PhD
Enhancing the Investment Performance of Yield-Based Strategies | Wes Gray, PhD, Jack Vogel, PhD
What Motivates Buy-Side Analysts to Share Recommendations Online? | Steven S. Crawford, Wes Gray, PhD, Bryan R. Johnson, Richard A. Price
Why Do Fund Managers Identify and Share Profitable Ideas? | Steven S. Crawford, Wes Gray, PhD, Andrew E Kern
Quantitative Momentum: A Practitioner’s Guide to Building a Momentum-Based Stock Selection System | Wes Gray and Jack Vogel
Quantitative Value, + Web Site: A Practitioner’s Guide to Automating Intelligent Investment and Eliminating Behavioral Errors | Wes Gray and Tobias Carlisle
DIY Financial Advisor: A Simple Solution to Build and Protect Your Wealth | Wes Gray, Jack Vogel, David Foulke
Embedded: A Marine Corps Adviser Inside the Iraqi Army | Wes Gray
Co-Chief Investment Officer, Chief Financial Officer, Portfolio Manager
Jack leads Alpha Architect’s team in all aspects, including trading, strategy design, operational efficiency, client communication, and more. His research into empirical asset pricing and behavioral finance has been published in multiple peer-reviewed academic journals.
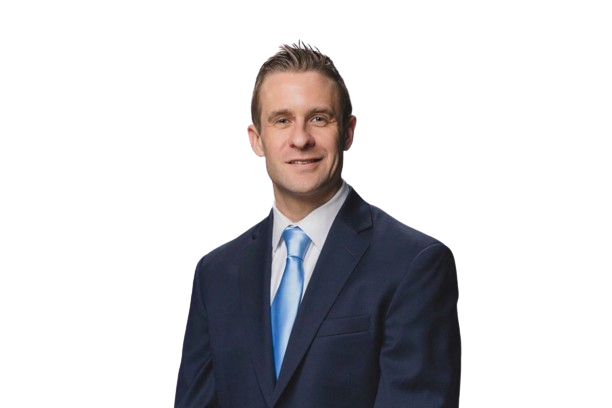
PhD Finance and an MS in Mathematics from Drexel University
BS in Mathematics and Education, summa cum laude from The University of Scranton
US Quantitative Value (QVAL)
US Quantitative Momentum (QMOM)
International Quantitative Value (IVAL)
International Quantitative Momentum (IMOM)
High Inflation & Deflation (HIDE)
Value Momentum Trend (VMOT)
Analyzing Valuation Measures: A Performance Horse Race over the Past 40 Years | Wes Gray, PhD, Jack Vogel, PhD
Why Do Enterprise Multiples Predict Expected Stock Returns? Steven S. Crawford, Wes Gray, PhD, Jack Vogel, PhD
Enhancing the Investment Performance of Yield-Based Strategies | Wes Gray, PhD, Jack Vogel, PhD
Quantitative Momentum: A Practitioner’s Guide to Building a Momentum-Based Stock Selection System | Wes Gray and Jack Vogel
DIY Financial Advisor: A Simple Solution to Build and Protect Your Wealth | Wes Gray, Jack Vogel, and David Foulke